· 4 min read · Updated 31 Aug 2026
By Correct Editorial — Compliance Research Desk
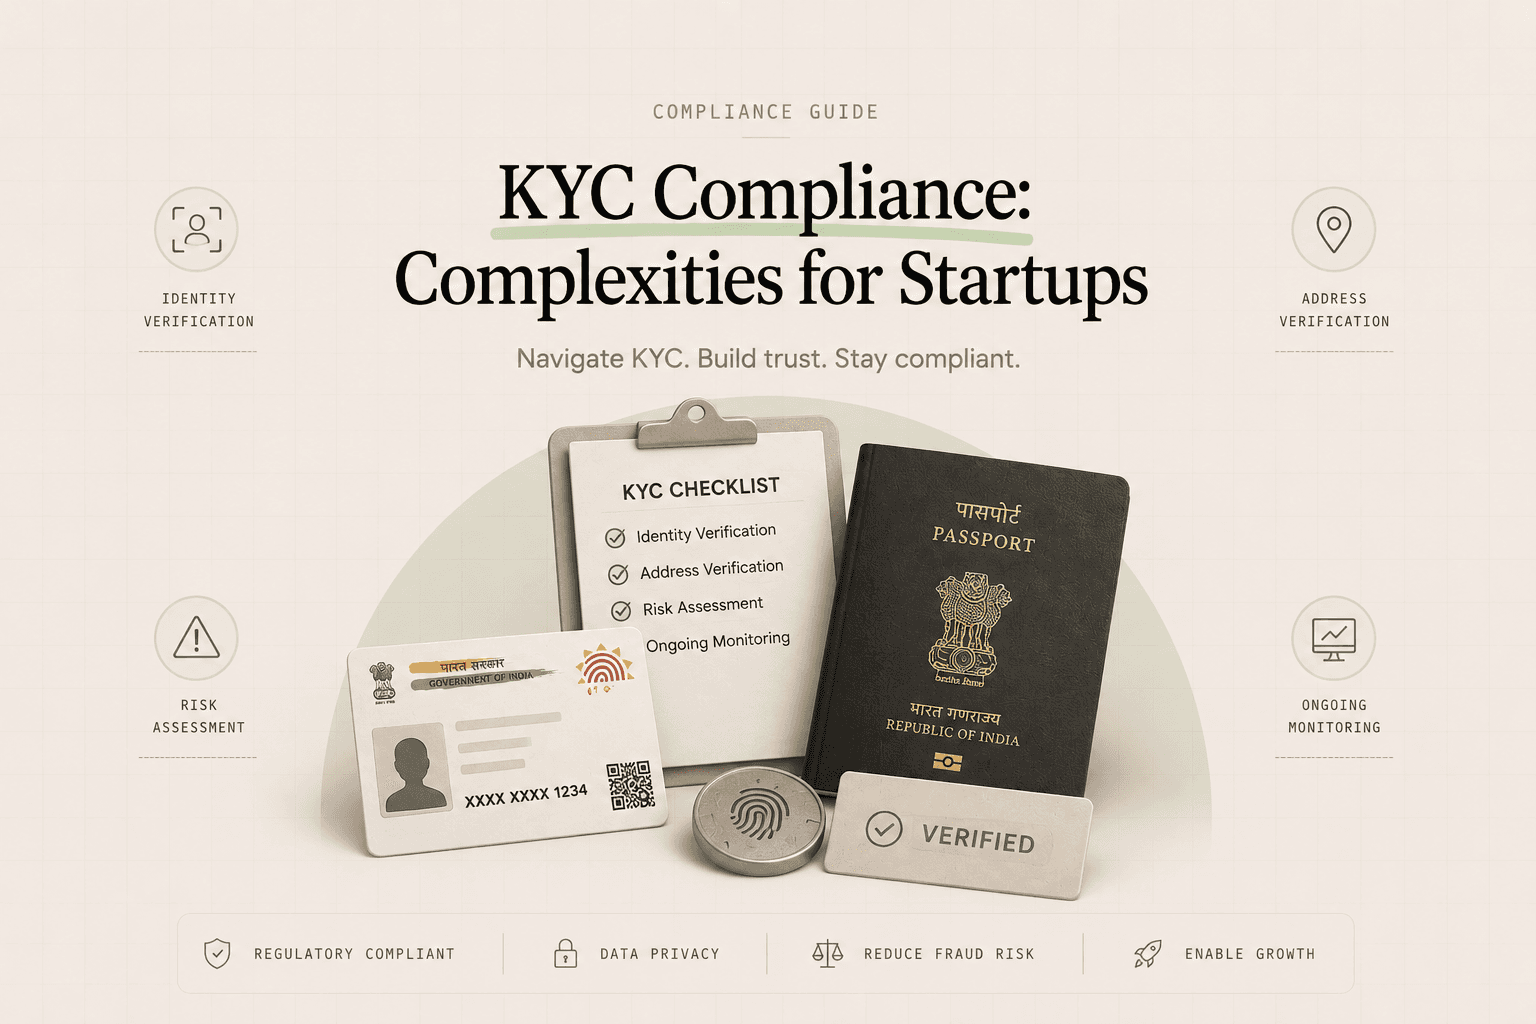
KYC Compliance Complexities for Startups
Published on: April 30, 2025
The start-up ecosystem in India has experienced remarkable growth over the past decade. From just 471 start-ups in 2016, there are now over 143,000 enterprises recognised by the Department for Promotion of Industry and Internal Trade (DPIIT), including more than 100 unicorns. This surge is primarily driven by the Fintech sector, which is projected to reach a market size of $150 billion by 2025. By the end of this year, the sector's Assets Under Management (AUM) are expected to surpass $1 trillion.
With the help of integrated ecosystems like Unified Payments Interface (UPI), Immediate Payment Service (IMPS), prepaid payment instruments (PPIs), and the National Electronic Toll Collection (NETC), India recorded over 80 billion digital transactions worth $36.5 trillion in FY22. This growth trajectory paints a promising future for the Fintech sector in India.
However, the sector's promising growth has been marred by instances of financial misconduct and improprieties. The Reserve Bank of India's (RBI) Annual Report for 2021–22 noted a 34% increase in frauds involving cards and internet banking, with 3,596 reported cases in FY22. The industry has faced issues such as:
- Fraudulent UPI transactions
- E-wallet thefts
- KYC data breaches
- Loan app scams
These incidents have led to a trust deficit.
To combat these challenges, regulators like the RBI, Securities and Exchange Board of India (SEBI), and the Insurance Regulatory and Development Authority (IRDAI) have implemented regulations such as:
- RBI Master Direction on Know Your Customer (KYC)
- SEBI's KYC Registration Agency Regulations
- IRDAI's AML/CFT guidelines
RBI’s KYC Master Direction Highlights
- Companies must adopt a risk-based approach with board-approved policies for periodic updates.
- Video Customer Identification Process (V-CIP) software must be tested before use.
- SOPs must be established to ensure process integrity.
- V-CIP must reject spoofed/foreign IP connections.
- Video recordings should include geo-tagging and date-time stamps.
- Software should detect spoofing and verify authenticity.
- Trained officials must conduct these processes.
KYC procedures are not just a formality but a crucial step for verifying transaction authenticity and user identity. These guidelines align with Financial Action Task Force (FATF) recommendations on Anti-Money Laundering (AML) and Counter Financing of Terrorism (CFT). They help institutions avoid transactions involving:
- Corruption
- Terrorism financing
- Fraud
- Money laundering
Therefore, regulations must be implemented in both letter and spirit, as they are the cornerstone of a secure financial system.
Challenges Faced by Startups
The Fintech sector is heavily funded by Venture Capital (VC) firms, which expect high growth rates. This often leads to:
- A focus on rapid client acquisition
- Incentives for shorter onboarding processes
- High drop-off rates due to lengthy onboarding
As a result, some companies cut corners:
- Incomplete KYC verifications
- Unethical practices like mis-selling and aggressive loan recovery
- High-interest charges
The RBI has imposed monetary penalties on several service providers for violating KYC and AML regulations. In her 2023 budget speech, the Finance Minister proposed a risk-based approach to simplify the KYC process.
Inclusion and Accessibility Challenges
Current regulations require proof of both current and permanent addresses, which can be challenging for:
- Migrant workers
- Nomadic communities
Electronic KYC (eKYC) and video KYC were introduced to streamline processes. However:
- Only ID documents authenticated via DigiLocker e-Sign are accepted
- DigiLocker requires an Aadhaar number
- Video KYC must be done in real-time by bank officials
- Resource-intensive and hard to scale
- The digital divide further hampers adoption
The Way Forward
KYC regulations must be more flexible to match the Fintech industry's pace. Suggestions include:
- Expanding the Central KYC Registry (CKYCR) to allow moderated access for Fintechs
- Enabling faster onboarding using shared KYC data
- Leveraging the Digital Personal Data Protection Act to facilitate consent-based data sharing
As more individuals complete their KYCs, redundant verifications can be reduced. This would support faster, more inclusive, and more secure financial services in India's digital economy.
What This Means Operationally for a Startup
The regulatory expectations described above are unusually prescriptive: they specify not only what must be verified but how the verification must be conducted. That has three practical consequences for a small team.
KYC is a system obligation, not a policy document. A board-approved policy satisfies the paperwork but not the requirement. The controls — spoofing detection, IP validation, geo-tagging, date-time stamping — live in software, which means KYC decisions are architectural decisions made early and expensive to revisit.
Evidence must survive the transaction. Video records, audit trails and verification artefacts have to be retrievable long after the onboarding they relate to. A startup that can complete verification but cannot produce the record of it months later has met the process and failed the obligation.
Trained officials are part of the control. Where the rules require a trained person in the loop, headcount planning becomes a compliance matter. Automating around that requirement is not available as an option.
The Cost of Getting It Wrong
The trust deficit described earlier is what makes enforcement in this area unusually direct. Failures do not simply attract a penalty; they tend to attract restrictions on the activity itself, which for an early-stage business is materially worse than a fine.
That asymmetry argues for building the verification and record-keeping layer before scale rather than after it. Retrofitting KYC controls onto a live customer base means re-verifying existing users, which is slower, costlier and considerably more visible to those users than doing it once at onboarding.
It also argues for keeping the evidence under the company's own control rather than solely inside a vendor's system. Where verification records sit with a third party, a change of provider becomes a compliance risk, not just a procurement decision.
For the wider set of obligations a startup accumulates alongside this one, see RegTech-as-a-Service and scaling compliance in India.
Frequently asked questions
- Which regulators set KYC rules for Indian fintech startups?
- Three regulators set the rules a fintech startup is likely to encounter. The Reserve Bank of India issues the Master Direction on Know Your Customer, SEBI issues the KYC Registration Agency Regulations, and IRDAI issues AML and counter-terrorist-financing guidelines. Which of them applies depends on whether the business handles payments, securities or insurance, and a company operating across those lines can fall under more than one.
- What does the RBI Master Direction require for video KYC?
- The Video Customer Identification Process carries specific technical obligations. The software must be tested before use and must reject spoofed or foreign IP connections, recordings must carry geo-tagging and a date-time stamp, and the system must be able to detect spoofing and verify authenticity. The process must be run by trained officials under a board-approved policy, with standard operating procedures documented to preserve process integrity.
- Why is KYC treated as more than a formality?
- KYC is the step that establishes both the authenticity of a transaction and the identity of the person behind it. The Indian rules follow the Financial Action Task Force recommendations on anti-money laundering and counter financing of terrorism, and their purpose is to keep institutions out of transactions connected to corruption, terrorism financing, fraud and money laundering. That is why regulators expect them to be implemented in spirit rather than as a checkbox.
- What prompted the tightening of KYC enforcement?
- Growth in digital finance came with a measurable rise in misconduct. The RBI Annual Report for 2021-22 recorded a 34 percent increase in frauds involving cards and internet banking, with 3,596 reported cases in FY22, alongside fraudulent UPI transactions, e-wallet thefts, KYC data breaches and loan app scams. The resulting trust deficit is what drove regulators to prescribe process detail rather than principles alone.